Thursday, November 19, 2026

A Nobel for Microfoundations

By Jon Murphy. He is a Professor of Economics at Nicholls State University.

"This year, the Sveriges Riksbank Prize in Economic Sciences in Memory of Alfred Nobel, colloquially called the Nobel Prize in Economics, went to Robert E. Hall of Stanford University and Michael Woodford of Columbia University for their work in “microeconomic foundations of macroeconomic stabilization.” Those five words do not adequately describe their contributions. Hall and Woodford are macroeconomists whose major works emerged when macro was in crisis. Old school Keynesian economics had dominated economic policy discussions since the 1940s. Generally speaking, Keynesians advocated fiscal policy tools (specifically taxes and spending) to stabilize the economy. For about 20 years, those tools seemed to work. But starting in the late 1960s and through the 70s, the macroeconomic relationships broke down. A seemingly impossible confluence of rising inflation and high unemployment characterized this period. Keynesian spending policies were becoming impotent. Critics of Keynesianism rose, and macroeconomics called out for new theories.

It was during this period that macroeconomics began to explore more microfoundations. That is, rather than treating the economy as a series of aggregates and their relations to one another, economists started to explore how aggregate macroeconomic factors were the results of individual behavior, institutions, and expectations. Stabilization policy could not be simply levers pulled or pushed by the policymaker. Rather, stabilization policy had to include theories on how people will react to such changes, as well as their expectations about the future. Models such as rational expectations, adaptive expectations, and the permanent income hypothesis were developed during this period as a means to explain why these Keynesian stabilization policies failed.

One of the models that came out of this period was Milton Friedman’s Permanent Income Hypothesis. The basic idea is that people base their consumption decisions not just on current income levels, but on future income levels as well. If a person can spend or save freely, they will spread out their consumption so as to avoid major changes over their lifetime. Temporary windfalls will be saved, so that when those funds run out, the standard of living will not drop. Consequently, a temporary increase in income (say, from a temporary tax cut) would not increase spending in the economy: individuals will know the tax cut is temporary and save the funds so that when the tax returns to the previous level, their level of spending will not fall dramatically. People would only react to permanent changes in their income.

Robert Hall built on the Permanent Income Hypothesis. In his 1978 Journal of Political Economy paper “Stochastic Implications of the Life Cycle-Permanent Income Hypothesis: Theory and Evidence,” Hall argued the Permanent Income Hypothesis is at least partially true: people do take the future into account when adjusting their consumption decisions. People will act according to expectations formed from available information. As information changes, so do their expectations and thus their consumption trends. However, since information changes are unpredictable and essentially random (if they weren’t, they wouldn’t be information changes and would already be taken into account by the consumer), changes in consumption are also unpredictable. Consumption changes, Hall argued, follow a random walk.

Hall’s argument has significant implications for macroeconomic stabilization policies. Under the Keynesian model, a given increase in income will mechanically generate a given increase in consumption, and thus national output. Readers with a background in economics will recognize this as the Keynesian multiplier. But what Hall showed, building off Friedman, is that such a mechanical relationship is conditional, at best. Whether the change in income was anticipated or unexpected, permanent or temporary, will influence how effective the policy will be. For example, if the government provides rebate checks every time there is a recession, the effectiveness of those rebates will fall over time. People will begin to anticipate them and adjust their behavior accordingly. Consequently, expected fiscal policy becomes impotent over time.

Hall’s random walk model does have its limitations, as he and co-author Frederic Mishkin noted in a 1982 paper in Econometrica entitled “The Sensitivity of Consumption to Transitory Income: Estimates from Panel Data on Households.” Not everyone can do such forward planning. Some households live paycheck-to-paycheck and do not have much flexibility to alter behavior. Consequently, they may face more limitations to consumption-smoothing and be more sensitive to changes in income. Thus, households can respond very differently to identical policies.

Michael Woodford’s work is a natural complement to Robert Hall’s. Whereas Hall focused on consumption and spending, Woodford focused on the central bank and the role of monetary policy. Woodford incorporates insights from three disparate but related microeconomic phenomena into a framework for understanding and evaluating monetary policy.

First, Woodford also built on the idea that households consume based not just on information about the present, but on expectations of the future as well. Those expectations are shaped by expectations of inflation, real interest rates, and future income. Like Hall, Woodford argued these expectations will influence how effective policy will be, but his focus was more on interest rate policy. If people anticipate changes in interest rates, they’ll take those changes into their planning.

Second, firms do not constantly change nominal prices; prices, at least in the short run, are sticky. Changing prices is costly and, to reduce costs, firms take into account expectations of future economic conditions when setting prices. Consequently, when aggregate demand shifts and nominal prices are sticky, firms will adjust output and employment rather than prices. This implies that monetary policy can have real effects in the short run, rather than simply producing inflation.

Third, the central bank influences activity not by changing the interest rate per se, but by changing its policy rate relative to the natural rate of interest. When the policy rate is below the natural rate, it will tend to stimulate demand. When the policy rate is above the natural rate, it will tend to reduce demand.

Taking these three insights together, Woodford developed a monetary theory that accounts for the expectations of firms and households. Specifically, his framework shows that the central bank affects macroeconomic behavior through both interest rate movements and setting expectations about future monetary policy. For example, say the Federal Reserve announces that it expects to keep interest rates low for an extended period. That changes people’s expectations of future monetary policy: there probably won’t be major increases in the future. In turn, that shapes their investing and saving behavior. Thus, even without changing rates, the Federal Reserve could influence current behavior. This communication has become known as “forward guidance.”

However, what matters here is that forward guidance is only effective to the extent people believe it. The central bank must have a credible commitment to its policies. If the central bank’s statements are not credible, forward guidance will not influence behavior, as it will not adjust expectations.

Both Hall’s and Woodford’s work falls under the macroeconomic school of thought called “New Keynesianism.” While the Nobel committee cited their work as research on “stabilization,” the academic debate continues about how effective these policies are. Regardless, both Hall and Woodford made significant theoretical advances in our understanding of how microfoundations can affect macroeconomic outcomes."

Related posts:

What do Nobel Prize Winners Muhammad Yunus and Edmund Phelps Have in Common?  (2006)

What The 2010 Nobel Prize Winners Studied (2010) ( Peter Diamond, Dale Mortensen, and Christopher Pissarides)

Some Information On This Year's Winners Of The Nobel Prize In Economics (2011) (Thomas Sargent and Christopher Sims)

Angus Deaton Wins The 2015 Nobel Prize In Economics  (2015)

Some Information About This Year's Winners Of The Nobel Prize In Economics (2016) (They are Oliver Hart and Bengt Holmström.)

Nobel for Economics Awarded to Authors of ‘Why Nations Fail’ and an Ex-IMF Figure: Daron Acemoglu, Simon Johnson and James Robinson are honored for their work on how institutions form and affect differences in prosperity (2024) 

Marginal Revolution has great posts on this year's winners of the Nobel Prize in economics (Philippe Aghion, Peter Howitt and Joel Mokyr): This is a prize for economic growth & creative destruction (2025) 

Marginal Revolution has four posts on this year's Nobel Prize winners (2026) 

Tuesday, November 17, 2026

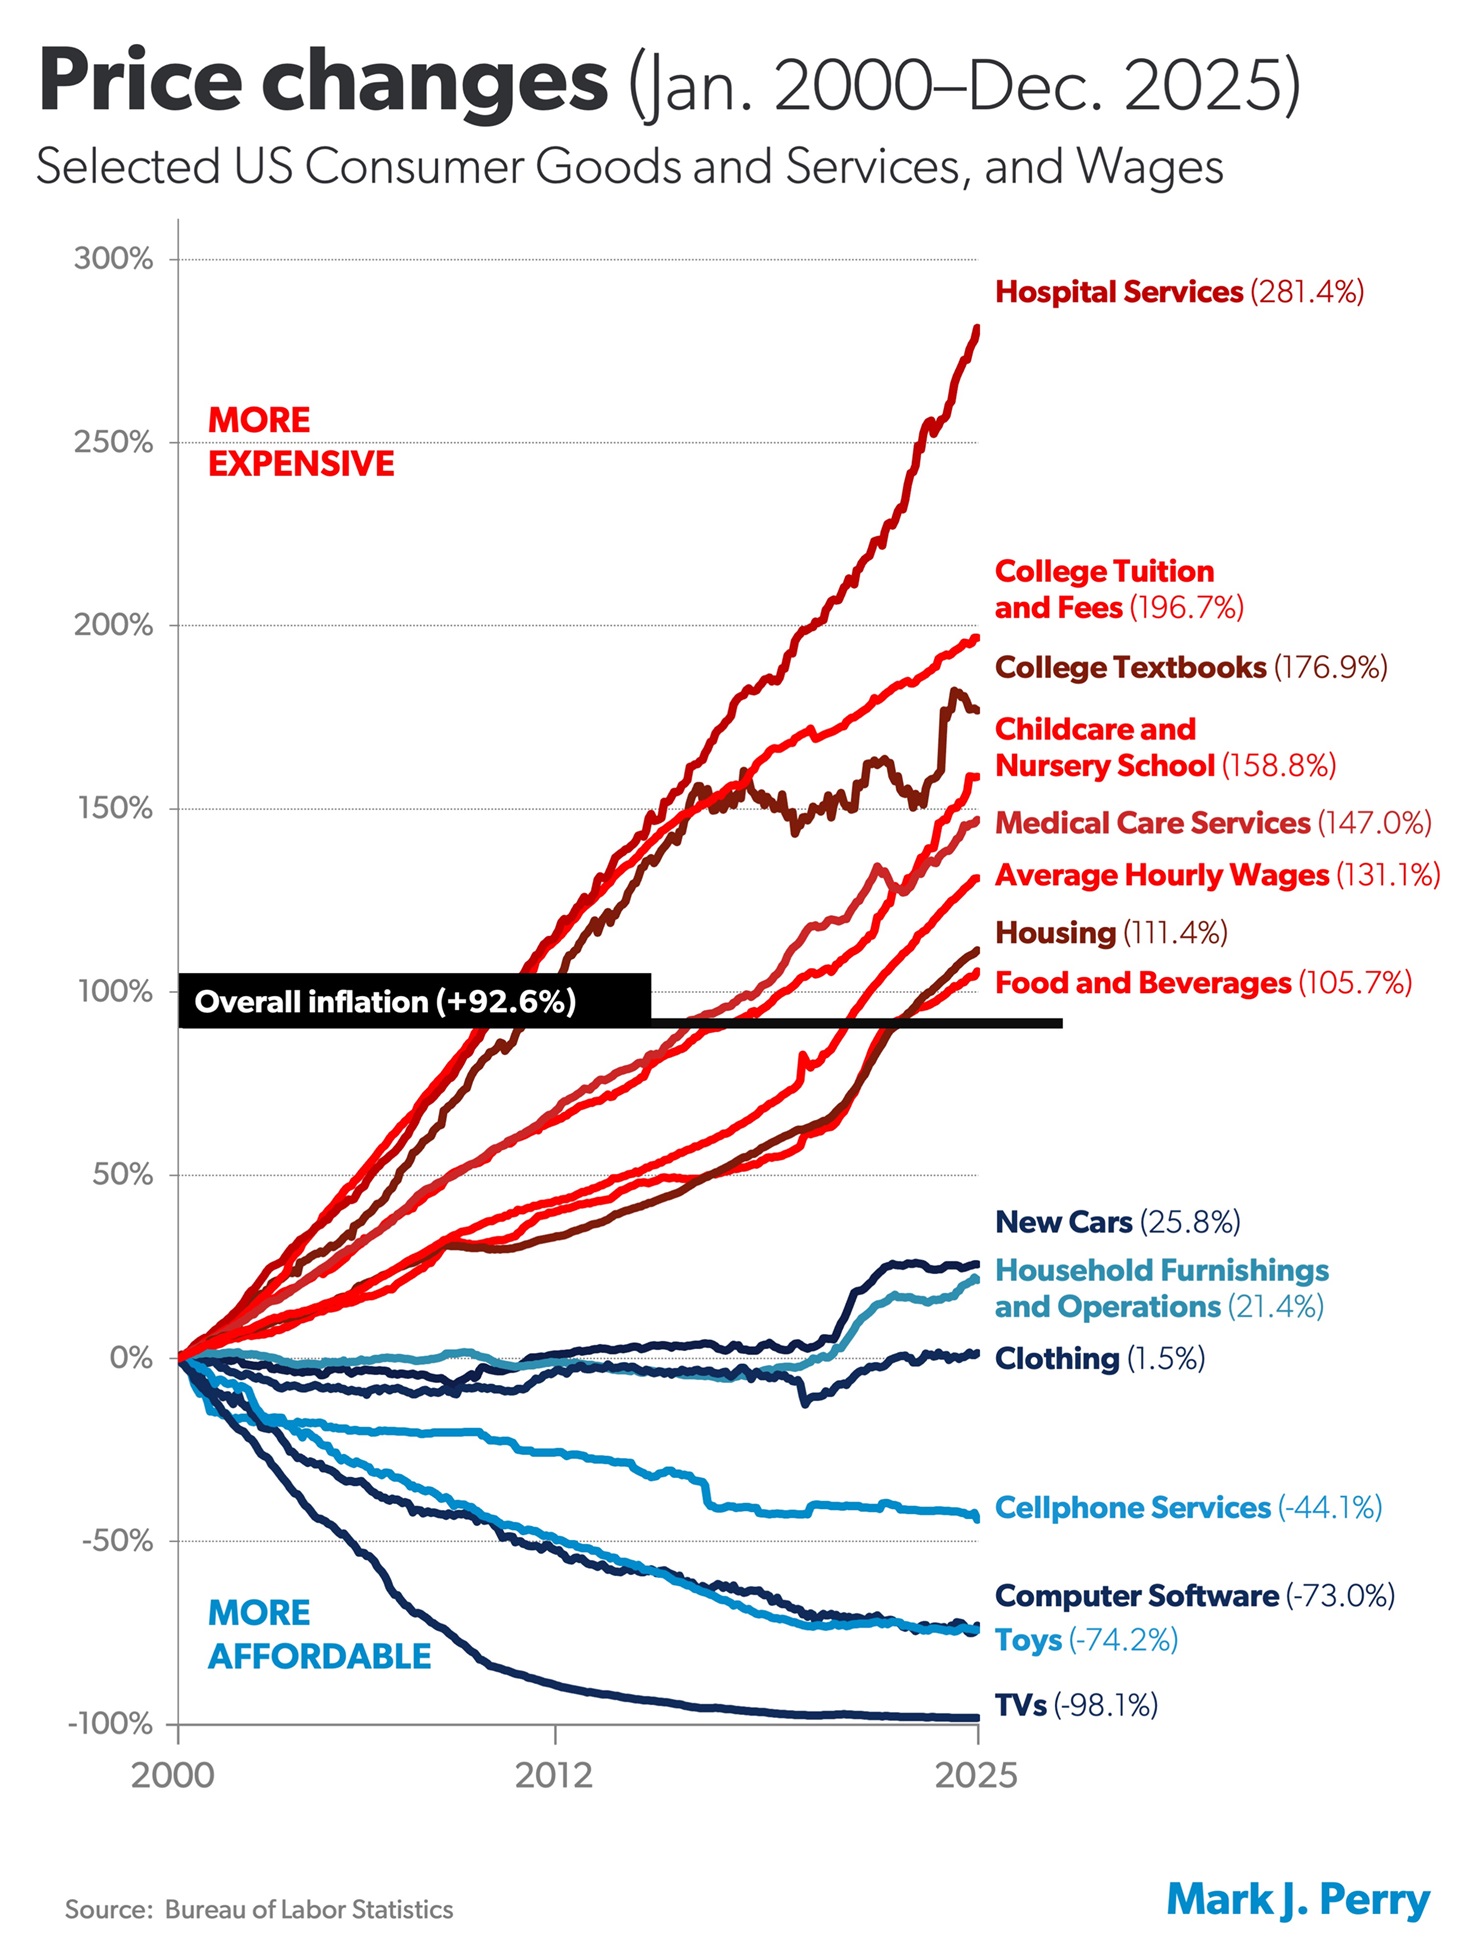
Rethinking the Cost of Living with Mark Perry’s “Chart of the Century”

Always compare prices to hourly wages to understand the true change in living standards. 

By Gale L. Pooley. Gale L. Pooley teaches U.S. economic history at Utah Tech University.

"Summary: Comparing nominal price changes to changes in average hourly wages from 2000 to 2025, we can see that many goods with rising dollar prices have become more affordable in time prices.


Professor Mark Perry from the American Enterprise Institute recently posted an updated version of his “Chart of the Century,” featuring price and wage data from the Bureau of Labor Statistics (BLS). The chart tracks 14 items over the 25-year period from January 2000 to December 2025. It also includes the overall inflation rate and changes in average hourly wages.

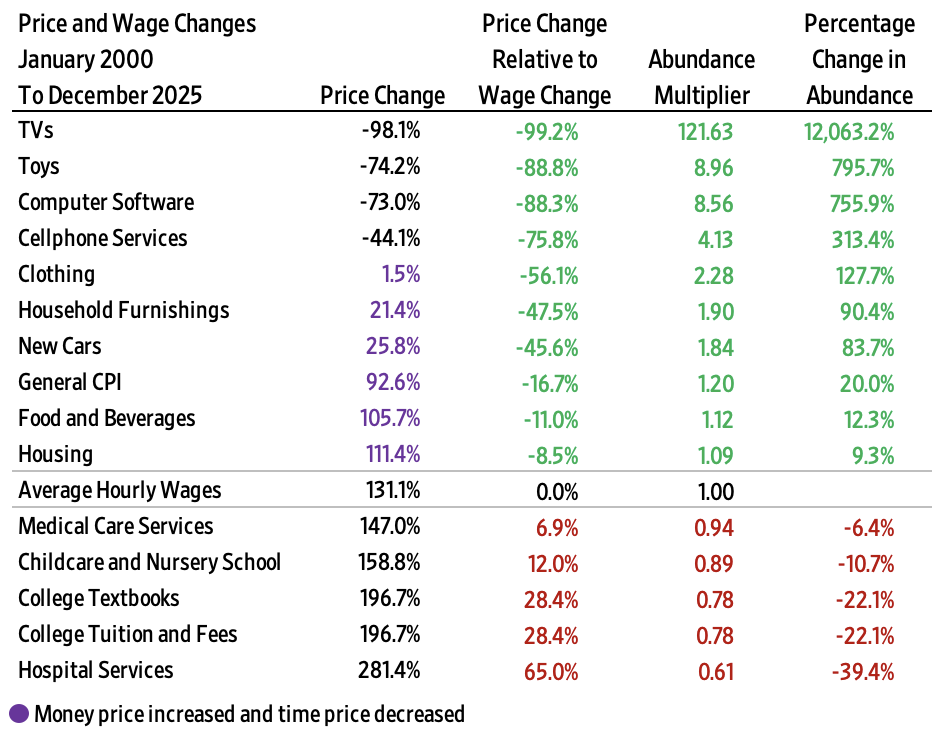
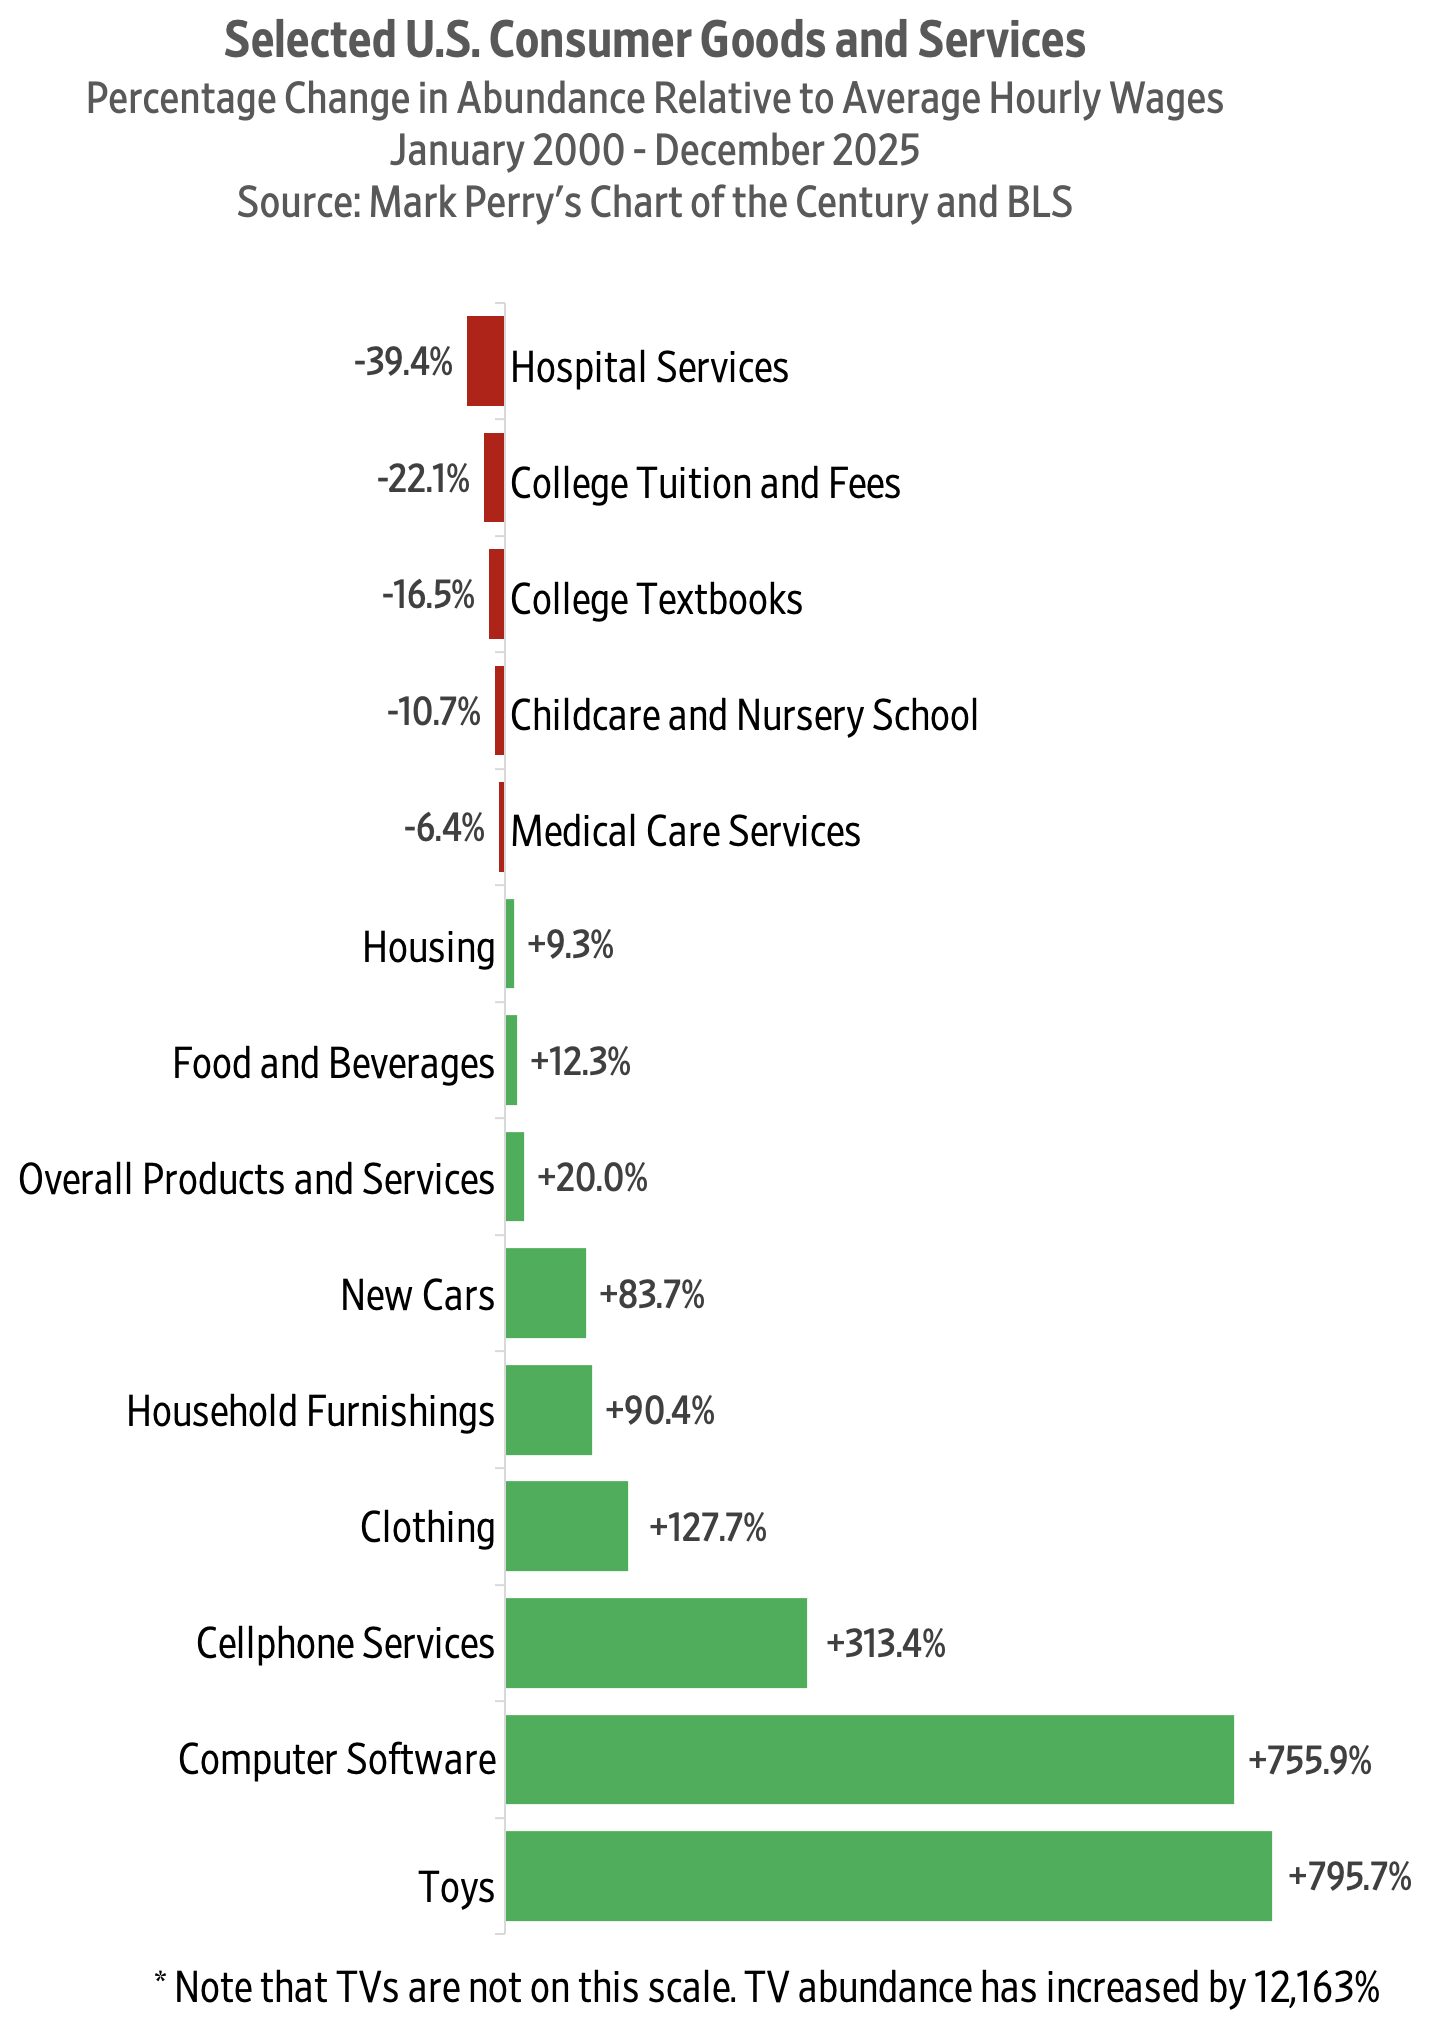
To examine the data from a different perspective, we calculated the change in the time prices of these 14 items relative to the change in the average hourly wage rate. We then calculated the abundance multiplier—a value indicating how many units you could buy today for the time it took to earn money to buy one unit in 2000. If there were no change, the abundance multiplier would equal one. A value below one indicates decreasing abundance, while a value above one reflects increasing abundance. We also calculated the percentage change in abundance for each item.

This analysis illustrates that things can become more expensive in dollar terms while simultaneously becoming more affordable in time prices. For instance, while the general Consumer Price Index (CPI) rose by 92.6 percent, average hourly wages increased by 131.1 percent. As such, time prices fell by 16.7 percent. For the time it took to earn enough money to purchase one CPI basket in January 2000, a consumer could purchase 1.2 baskets in December 2025—an abundance increase of 20 percent.

Notably, categories such as housing, food and beverages, new cars, household furnishings, and clothing all increased in money prices; however, after adjusting for rising wages, they all became more affordable in time-price terms. Although 10 of the 14 items rose in nominal prices over the 25-year period, only five had higher time prices when accounting for the 131.1 percent increase in hourly wages.

Find more of Gale’s work at his Substack, Gale Winds."

Sunday, November 15, 2026

The Influence of In-Store Music on Wine Selections

By A. C. North, David J Hargreaves & Jennifer McKendrick. 

Tastes and preferences are a shift factor for demand curves. But we don't usually say much about how tastes are formed in economics. This might be an example. 

"Abstract 

This field study investigated the extent to which stereotypically French and German music could influence supermarket customers' selections of French and German wines. Music with strong national associations should activate related knowledge and be linked with customers buying wine from the respective country. Over a 2-week period, French and German music was played on alternate days from an in-store display of French and German wines. French music led to French wines outselling German ones, whereas German music led to the opposite effect on sales of French wine. Responses to a questionnaire suggested that customers were unaware of these effects of music on their product choices. The results are discussed in terms of their theoretical implications for research on music and consumer behavior and their ethical implications for the use of in-store music.

Related posts: 

Is the TV show Yellowstone changing consumer's taste in clothing? (2023) 

Are TikTok influencers changing consumers' tastes? (2023)

James Buchanan, Frank Knight and John Stuart Mill on choice and utility functions (2022)

Has the pandemic changed tastes (which change demand)? (2020)

Boats, Pools and Home Furnishings: How the Lockdown Transformed Our Spending Habits (2020)

Are some blue jeans really Democratic and others Republican? (2019)

TV chefs showcase recipes using mutton, prices jump (2019)

Grocery stores try to alter the tastes and preferences of men (2018)

Are Your Friends Making You Fat? (2009)

What If You Discovered That You Liked Celine Dion? (How One Company Tried To Determine Buyers' Tastes And Preferences) (2009)

Friday, November 13, 2026

Why is gasoline suddenly under $4 a gallon?

By Willa Rubin of NPR. After excerpts I posted a timeline chart of how gas prices have changed since 1918 adjusted for inflation. They are not especially high right now by historical standards.

"The price crossed below the $4 threshold on Tuesday, and is currently down to a national average of $3.94 for a gallon of regular. Prices have dipped about 40 cents over the past month" 

gasoline prices are dropping for a more banal reason: "For now, it's the seasonal shift, not politics, driving the relief at the pump."

"Gas prices often ease in the fall.

One reason: It's no longer summer, which is the peak season for gas. (Fewer people drive in colder weather, AAA points out.) With less demand, there's a touch more gas on the market.

Refineries also finish their annual maintenance by late fall. So that adds a bit more gas to go around.

And the blend of gasoline that's on the market gets cheaper.

Refineries make two types of gasoline every year: summer and winter blends. The summer blend produces less smog, because it evaporates less quickly in the heat; the winter blend helps engines start up in freezing weather, and uses a bit more butane, which helps lower its cost.

(Normally, the switch happens around September 15. This year, the Environmental Protection Agency and the Department of Energy said the switch would happen on September 1, citing gasoline prices that have been driven up by the war in Iran.)"

The main driver is the falling price of Brent crude oil, which is now down to about $90 a barrel, and which is what refineries need to make gasoline, diesel and jet fuel.

That price is falling because there's a bit more oil coming out of the Middle East via pipelines, and because market traders have rejoiced at the intensifying diplomatic efforts between the U.S. and Iran."

Related posts:

Factors Influencing The Price Of Gas (2011)

Price-gouging laws can backfire (2017)

People say the president can control gas prices if the president belongs to the other party (2017)

Why are refiners' profits so high and can anything bring down gas prices? (2022) 

Gas Station Owners, Blamed When Prices Rose, Face Risks as Prices Fall (2022) 

California Has a Gas-Price Mystery: Too High, but Why? (2023)

Why Gasoline Prices Are Rising Faster Than Usual This Year: Fuel costs are once again driving inflation. Don’t panic. (2024)

The graph below is from a great blog post by Tim McMahon of InflationData.com. See Inflation Adjusted Gasoline Prices. He gives a history of gas prices with lots of tables.

Image 


Thursday, November 12, 2026

Gina Hinojosa Wants To Freeze Electricity Rates in Texas. New Jersey Shows Why That Won't Work.

In New Jersey, a rate freeze touched only part of the bill, and in some cases left ratepayers with higher bills than before.

By Tosin Akintola of Reason. 

"When Democrat Gina Hinojosa is sworn in as Texas governor in January, one of her first acts, "within an hour of taking the oath of office," she recently told The Texas Tribune, will be to "declare a high-cost emergency in the state of Texas and issue an emergency executive order to: one, suspend the gas and diesel tax; and two, freeze electricity rates." 

Hinojosa—who tied increases in property taxes and electricity bills to Republican Gov. Greg Abbott's policies—promised during her campaign that if elected, she would "direct the Public Utility Commission to freeze the rates residential customers pay until we have laws to ensure that data centers and other high-load users pay for themselves." 

With Texans seeing a 3.3 percent increase in the average electricity price for residential customers between August 2025 and August 2026—roughly in line with the national increase—the state's electorate clearly found Hinojosa's pledge compelling. However, it's unclear if Hinojosa actually has the power to follow through on her campaign promise. 

In Texas' decentralized market, retail providers, not regulators, set electricity prices. This means Hinojosa has very little authority over residential prices, and her order would not lower costs. But as Click2Houston.com points out, Hinojosa could still impact prices; she could use her influence over the state budget "to push lawmakers toward her priorities," including forcing data centers to pay more. Of course, this would do little to address the primary cause of nationwide electricity spikes: transmission and distribution charges. 

Instead of Texas imposing price controls on the free market, Hinojosa could learn from the mistakes of New Jersey Gov. Mikie Sherrill, a fellow Democrat who has failed to meaningfully lower electricity prices in her state despite signing an executive order that declared a state of emergency and froze rate hikes by the state's utilities. 

Sherrill realized that even if she froze rates, it wouldn't erase the factors driving higher electricity prices, such as the supply and transmission costs providers pay. In June, to offset the increases utilities typically pass on to customers, Sherrill signed off on a budget authorization that allocates $500 million to provide ratepayers short-term relief. Yet in October, a CBS News report found that even after the rate freeze, utility costs in the Garden State remained high, with one resident remarking her electricity bill had "nearly doubled."

In July, the consulting firm E3 released a report—commissioned by Sherrill for the New Jersey Board of Public Utilities—that found that changes to state policy mainly affect distribution, which is "roughly a quarter" of the charges on residents' electricity bills, and that "no single reform or modernization option" could be presented as a standalone fix. 

It's not just New Jersey that has tried (and failed) to bring down utility costs by freezing electricity rates; last July Georgia's Public Service Commission unanimously approved an agreement to freeze base power rates for at least three years. A year after the freeze was implemented, the average electricity price for residential customers in Georgia rose by 2.3 percent. Meanwhile, in October, Virginia Democratic Gov. Abigail Spanberger called for a six-year freeze on residential electricity rates as a condition for approving the proposed $67 billion merger between utilities Dominion Energy and NextEra Energy. 

Regardless of where it's proposed, a rate freeze is a superficial fix for a problem that requires less government thumb on the scale, not more. 

At least one Democratic governor has declined to use rate freezes as a temporary panacea for rising energy costs. In a March appearance on CBS 2's "The Point," New York Gov. Kathy Hochul was asked if she thought a "two-year moratorium or freeze on utility rates statewide" was "doable." She quickly rejected the idea, favoring an "all-of-the-above approach to find more sources of energy to help drive down [costs]." 

What rate freezes like Hinojosa's miss is that states have little direct impact on electric prices. As the E3 report notes, "Most of a typical bill…is set in federal and regional markets with limited ability at the state level to influence those costs." 

Still, that doesn't make the idea behind these policies—that government should interfere in the market—any less harmful.

Without the price signals they receive from electricity rates, utilities can't properly plan for upgrades, expansion, or future demand. Freezing electricity rates clearly polls well as policy, but it works better on the campaign trail than in practice."

Wednesday, November 11, 2026

Celebrating Russian Novelist Fyodor Dostoevsky

Nov. 11 is his birthday. One of his famous books is Crime and Punishment.

Below are some passages that relate to economics and one sounds like the invisible hand.  All of the passages can be found at https://www.gutenberg.org/files/2554/2554-h/2554-h.htm.

From Part I, Chapter 2:

"But Mr. Lebeziatnikov who keeps up with modern ideas explained the other day that compassion is forbidden nowadays by science itself, and that that's what is done now in England, where there is political economy." (economics used to be called political economy)"

From Part II, Chapter 5:

"if I were told, 'love thy neighbour,' what came of it?" Pyotr Petrovitch went on, perhaps with excessive haste. "It came to my tearing my coat in half to share with my neighbour and we both were left half naked. As a Russian proverb has it, 'Catch several hares and you won't catch one.' Science now tells us, love yourself before all men, for everything in the world rests on self-interest. You love yourself and manage your own affairs properly and your coat remains whole. Economic truth adds that the better private affairs are organised in society--the more whole coats, so to say—the firmer are its foundations and the better is the common welfare organised too. Therefore, in acquiring wealth solely and exclusively for myself, I am acquiring, so to speak, for all, and helping to bring to pass my neighbour's getting a little more than a torn coat; and that not from private, personal liberality, but as a consequence of the general advance." The idea is simple, but unhappily it has been a long time reaching us, being hindered by idealism and sentimentality. And yet it would seem to want very little wit to perceive it."

From Part III, Chapter 5:

"“Not quite, that’s true,” Razumihin agreed at once, getting warm and hurried as usual. “Listen, Rodion, and tell us your opinion, I want to hear it. I was fighting tooth and nail with them and wanted you to help me. I told them you were coming.… It began with the socialist doctrine. You know their doctrine; crime is a protest against the abnormality of the social organisation and nothing more, and nothing more; no other causes admitted!…”

“You are wrong there,” cried Porfiry Petrovitch; he was noticeably animated and kept laughing as he looked at Razumihin, which made him more excited than ever.

“Nothing is admitted,” Razumihin interrupted with heat. “I am not wrong. I’ll show you their pamphlets. Everything with them is ‘the influence of environment,’ and nothing else. Their favourite phrase! From which it follows that, if society is normally organised, all crime will cease at once, since there will be nothing to protest against and all men will become righteous in one instant. Human nature is not taken into account, it is excluded, it’s not supposed to exist! They don’t recognise that humanity, developing by a historical living process, will become at last a normal society, but they believe that a social system that has come out of some mathematical brain is going to organise all humanity at once and make it just and sinless in an instant, quicker than any living process! That’s why they instinctively dislike history, ‘nothing but ugliness and stupidity in it,’ and they explain it all as stupidity! That’s why they so dislike the living process of life; they don’t and a living soul! The living soul demands life, the soul won’t obey the rules of mechanics, the soul is an object of suspicion, the soul is retrograde! But what they want though it smells of death and can be made of india-rubber, at least is not alive, has no will, is servile and won’t revolt! And it comes in the end to their reducing everything to the building of walls and the planning of rooms and passages in a phalanstery! The phalanstery is ready, indeed, but your human nature is not ready for the phalanstery—it wants life, it hasn’t completed its vital process, it’s too soon for the graveyard! You can’t skip over nature by logic. Logic presupposes three possibilities, but there are millions! Cut away a million, and reduce it all to the question of comfort! That’s the easiest solution of the problem! It’s seductively clear and you mustn’t think about it. That’s the great thing, you mustn’t think! The whole secret of life in two pages of print!”

“Now he is off, beating the drum! Catch hold of him, do!” laughed Porfiry. “Can you imagine,” he turned to Raskolnikov, “six people holding forth like that last night, in one room, with punch as a preliminary! No, brother, you are wrong, environment accounts for a great deal in crime; I can assure you of that.”

“Oh, I know it does, but just tell me: a man of forty violates a child of ten; was it environment drove him to it?”

“Well, strictly speaking, it did,” Porfiry observed with noteworthy gravity; “a crime of that nature may be very well ascribed to the influence of environment.”"

To see what phalanstery is go to Phalanstère at Wikipedia. Excerpt:

"A phalanstère (or phalanstery) was a type of building designed for a self-contained utopian community, ideally consisting of 500–2,000 people working together for mutual benefit, and developed in the early 19th century by Charles Fourier. Fourier chose the name by combining the French word phalange (phalanx, an emblematic military unit in ancient Greece), with the word monastère (monastery)."

Tuesday, November 10, 2026

The Seasonally Adjusted CPI Was Up 0.3503% in October

Here are the changes in the seasonally adjusted CPI for the six months ending in Sept.: 

April 0.6400%
May 0.4729%
June -0.4220%
July 0.0737%
Aug. 0.3960%
Sept. 0.649%% 
 
See Consumer Price Index for All Urban Consumers: All Items in U.S. City Average from FRED (Federal Reserve Economic Data) compiled by the Research Division at the Federal Reserve Bank of St. Louis for data on the seasonally adjusted CPI.  

That site shows a graph but if you click on the Download button you will get the actual numbers in Microsoft Excel.

The Consumer Price Index for All Urban Consumers: All Items in U.S. City Average (CPIAUCSL) was 336.298 in Sept. and 337.476 in Oct. Since 337.476/336.298 = 1.003503, that means it was up 0.3503%. If we had that every month for 12 months the CPI would be up 4.29%. 

There was no CPI report in Oct. 2025 because of the government shutdown. So I took the average of Sept. and Nov. of 2025 to get 324.654. There is no guarantee that it would have been higher in Oct. than Sept. because sometimes the CPI does go down in a given month. But most months it does increase.

Using 324.654 as an estimate for Oct. 2025 then 337.476/324.654 = 1.0395. That means it would be up 3.95% over the last 12 months. 

If I do a similar estimate for the the non-seasonally adjusted CPI it would be up 4.02%. So pretty close to the seasonally adjusted CPI. This is well above the Fed's target of 2.0% (although they prefer to use the Personal Consumption Expenditures Price Index which was 3.6% higher in Sept. 2026 than Sept. 2025). 

For more information see Consumer prices rose 0.4% in October, more than expected, complicating Fed’s inflation fight by Jeff Cox of CNBC. Excerpt:

"Costs for goods and services rose more than expected in October, providing fresh warning signs for the Federal Reserve in its fight to lower inflation.

The consumer price index, a broad gauge of costs across the U.S. economy, increased a seasonally adjusted 0.4% for the month, the Bureau of Labor Statistics reported Tuesday. Economists surveyed by Dow Jones had been looking for a 0.3% increase.

Stripping out volatile food and energy, so-called core CPI increased 0.3% against the forecast for a 0.2% gain.

The headline CPI had increased 0.6% in September while core was up 0.3%.

The report comes at a critical juncture for the Federal Reserve as it considers its next interest-rate move. Speaking Tuesday morning in London ahead of the CPI release, Fed Governor Christopher Waller said a hot inflation report could push him toward advocating for a half-point increase in December, and specifically said such a hike should be on the table if core CPI was “around 0.3.”" 

The article also discusses what types of products are going up in price and what is going down. 

Related material: 

Consumer Price Index for All Urban Consumers: All Items Less Food and Energy in U.S. City Average (CPILFESL) This is also from from FRED (Federal Reserve Economic Data), compiled by the Research Division at the Federal Reserve Bank of St. Louis. It has the seasonally adjusted core CPI.


The Bureau of Labor Statistics makes seasonal adjustments. See Consumer Price Index Summary.
 
The table below has the annual inflation rate since 1914 in the columns labeled CPI %Ch. or CPI percentage change. It is from Consumer Price Index Data from 1913 to 2026 and is not seasonally adjusted. It is also the December to December change in the CPI. That site also looks at how the 12 month average for the CPI changed from one year to the next.
 

Year

CPI %Ch.


Year

CPI %Ch.


Year

CPI %Ch.


Year

CPI %Ch.

1914

1


1944

2.3


1974

12.3


2004

3.3

1915

2


1945

2.2


1975

6.9


2005

3.4

1916

12.6


1946

18.1


1976

4.9


2006

2.5

1917

18.1


1947

8.8


1977

6.7


2007

4.1

1918

20.4


1948

3


1978

9


2008

0.1

1919

14.5


1949

-2.1


1979

13.3


2009

2.7

1920

2.6


1950

5.9


1980

12.5


2010

1.5

1921

-10.8


1951

6


1981

8.9


2011

3

1922

-2.3


1952

0.8


1982

3.8


2012

1.7

1923

2.4


1953

0.7


1983

3.8


2013

1.5

1924

0


1954

-0.7


1984

3.9


2014

0.8

1925

3.5


1955

0.4


1985

3.8


2015

0.7

1926

-1.1


1956

3


1986

1.1


2016

2.1

1927

-2.3


1957

2.9


1987

4.4


2017

2.1

1928

-1.2


1958

1.8


1988

4.4


2018

1.9

1929

0.6


1959

1.7


1989

4.6


2019

2.3

1930

-6.4


1960

1.4


1990

6.1


2020

1.4

1931

-9.3


1961

0.7


1991

3.1


2021

7

1932

-10.3


1962

1.3


1992

2.9


2022

6.5

1933

0.8


1963

1.6


1993

2.7


2023

3.4

1934

1.5


1964

1


1994

2.7


2024

2.9

1935

3


1965

1.9


1995

2.5


         2025    

          2.7

1936

1.4


1966

3.5


1996

3.3


1937

2.9


1967

3


1997

1.7


1938

-2.8


1968

4.7


1998

1.6


1939

0


1969

6.2


1999

2.7


1940

0.7


1970

5.6


2000

3.4


1941

9.9


1971

3.3


2001

1.6


1942

9


1972

3.4


2002

2.4


1943

3


1973

8.7


2003

1.9


Here is a timeline graph of this data: